To file a water damage claim in Florida: stop the source, photograph everything, report the claim promptly (generally within one year of the loss for new claims), start drying to prevent more damage, and keep every receipt and record. For policies issued on or after January 1, 2023, you can't assign your benefits to a contractor, so you stay in charge of the claim. This is general information, not legal advice.
What Florida homeowners policies usually cover
| Situation | Typical treatment |
|---|---|
| Sudden pipe burst or appliance hose failure | Often covered (the pipe or appliance repair itself usually isn't) |
| Slow leak over weeks or months | Often excluded as long-term seepage or wear and tear |
| Rising floodwater from outside | Excluded; needs a separate flood policy |
| Wind-driven rain through storm damage | Often covered, with a hurricane deductible for named storms |
| Sewer or drain backup | Often needs a water backup endorsement |
| Mold | Often limited to a set dollar amount or excluded |
Your declarations page and endorsements decide what applies to you. Ask your agent if you're not sure.
The assignment of benefits (AOB) ban
Florida's SB 2-A, signed in December 2022, prohibits assigning post-loss benefits under residential and commercial property insurance policies issued on or after January 1, 2023. In practice, a restoration company can't take over your claim on a newer policy. You remain responsible for the claim and for paying the contractor under your agreement. Read every form before signing, and make sure it's a service agreement, not a transfer of your insurance rights.
Deadlines to know
- New or reopened claims: generally must be reported within one year of the date of loss.
- Supplemental claims: generally within 18 months.
- Your policy may also require "prompt" notice, so report as soon as you can.
Step-by-step: filing the claim
- Prevent further damage: stop the water and start extraction and drying.
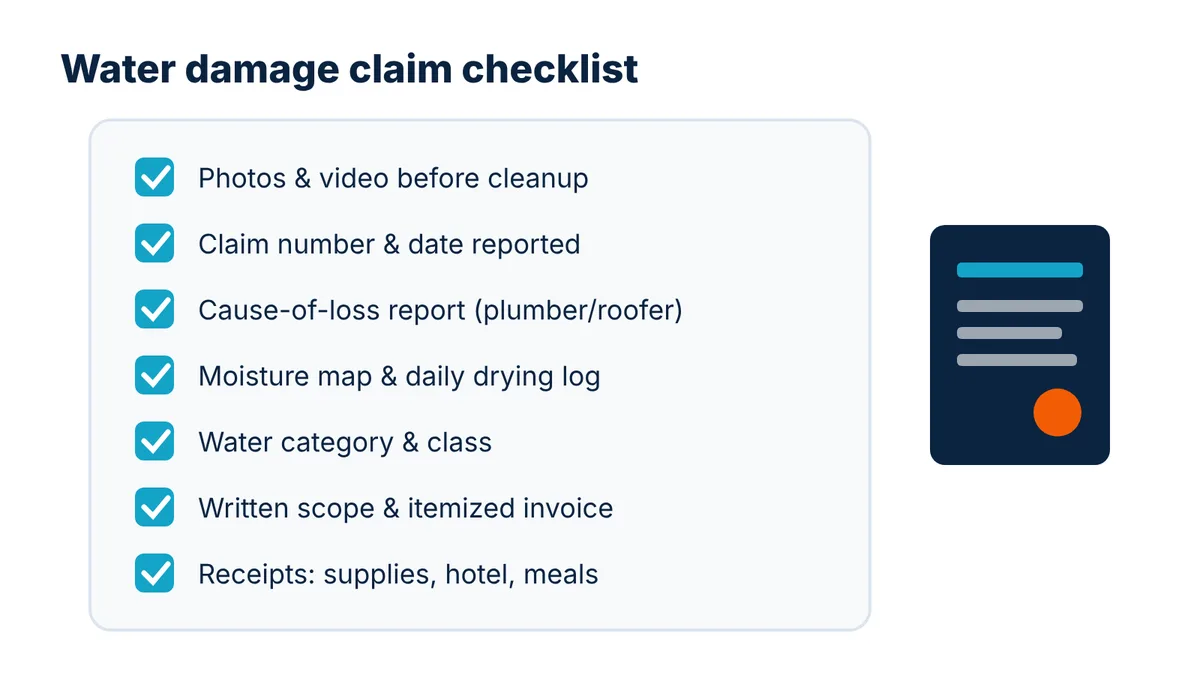
- Document: photos, video, the water line on walls, and the failed part.
- Report to your insurer by phone or app; note the claim number and adjuster's name.
- Get a cause-of-loss report from the plumber, roofer or HVAC technician.
- Collect restoration records: moisture map, drying log, water category and class, written scope and invoice.
- Make a contents list with photos, approximate age and value.
- Meet the adjuster and walk them through your photos and records.
- Review the estimate and ask questions about anything you don't understand.
Mistakes that hurt claims
- Waiting weeks to report the loss.
- Throwing out damaged items before photographing them.
- Not drying the home, letting mold develop.
- Signing documents that transfer your rights without reading them.
- Paying in cash without an itemized invoice.
Where to get help
If you have questions about your policy or a dispute, you can contact your agent, the Florida Department of Financial Services consumer helpline, a licensed public adjuster, or a Florida attorney. A restoration company documents the damage and the work but, under Florida law, can't adjust or negotiate your claim for you. For the restoration side, see our insurance documentation page or call (786) 732-2700.
Frequently asked questions
How long do I have to file a water damage claim in Florida?
Under the 2022 reforms, new or reopened property claims generally must be reported within one year of the date of loss, and supplemental claims within 18 months. Report as soon as possible.
Does Florida homeowners insurance cover a slow leak?
Usually not. Many policies exclude damage from continuous or repeated leaks over time. Sudden, accidental discharges are more commonly covered.
Can a contractor file the claim for me?
For policies issued on or after January 1, 2023, you can't assign your post-loss benefits to a contractor. You file and manage the claim yourself or with a licensed public adjuster or attorney.
Is flood damage covered by homeowners insurance?
Rising floodwater is usually excluded. Flood coverage comes from a separate NFIP or private flood policy.
Will my insurer pay for hotel stays during repairs?
Many homeowners policies include additional living expenses when a covered loss makes the home unlivable. Keep receipts and ask your adjuster.
More water damage guides
- Water Damage in Your Home: What to Do in the First 24 Hours
- Water Damage Categories and Classes, Explained Simply
- AC Leaking Water Inside the House? Causes and What to Do
- Hurricane Season Water Damage Prep for Tamiami Homes
- How Long Does Water Damage Restoration Take?
Related services: Flood Damage Restoration · Storm & Hurricane Water Damage · Water Damage Insurance Documentation · Water damage restoration in Tamiami