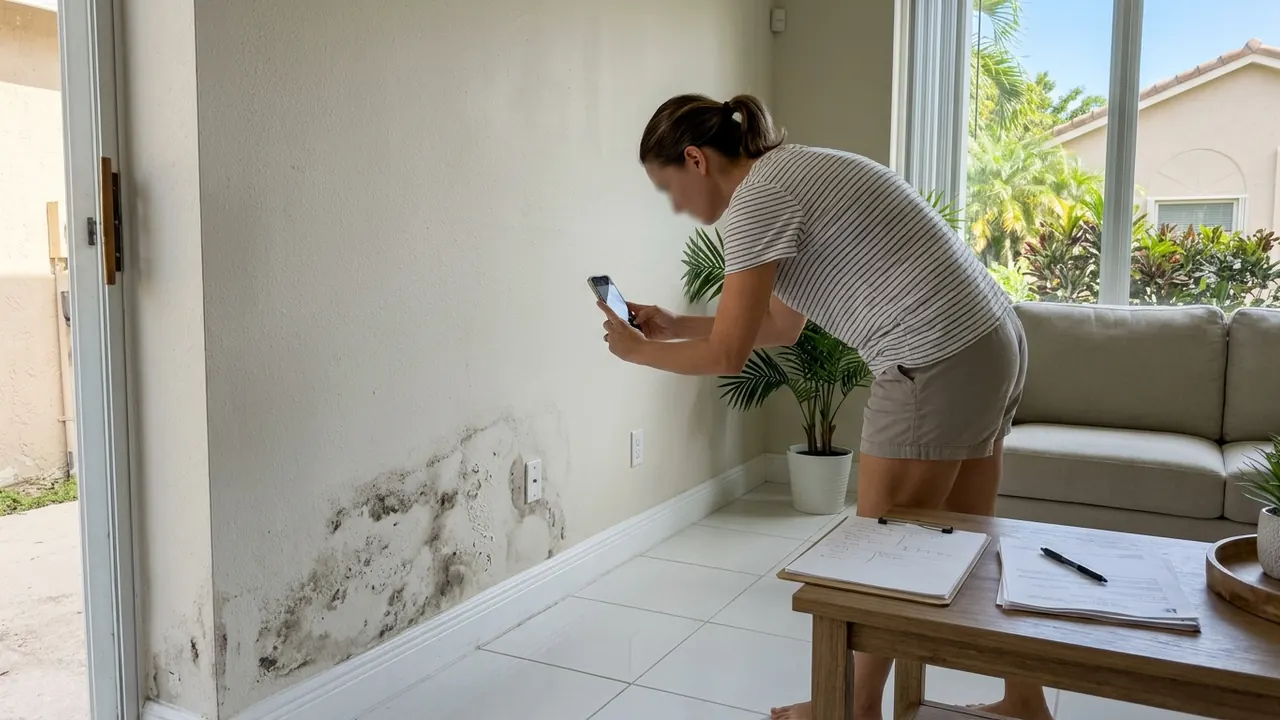
To support a water damage claim in Florida, report the loss to your insurer promptly, photograph everything before it's moved, keep removed materials or samples if asked, save every receipt, and get moisture readings and a written scope from the restoration team. Since the 2022 reforms, property policies issued on or after January 1, 2023 don't allow an assignment of benefits (AOB) to a contractor, so you stay in charge of your claim. This page is general information, not legal advice.
The first 24 hours: claim checklist
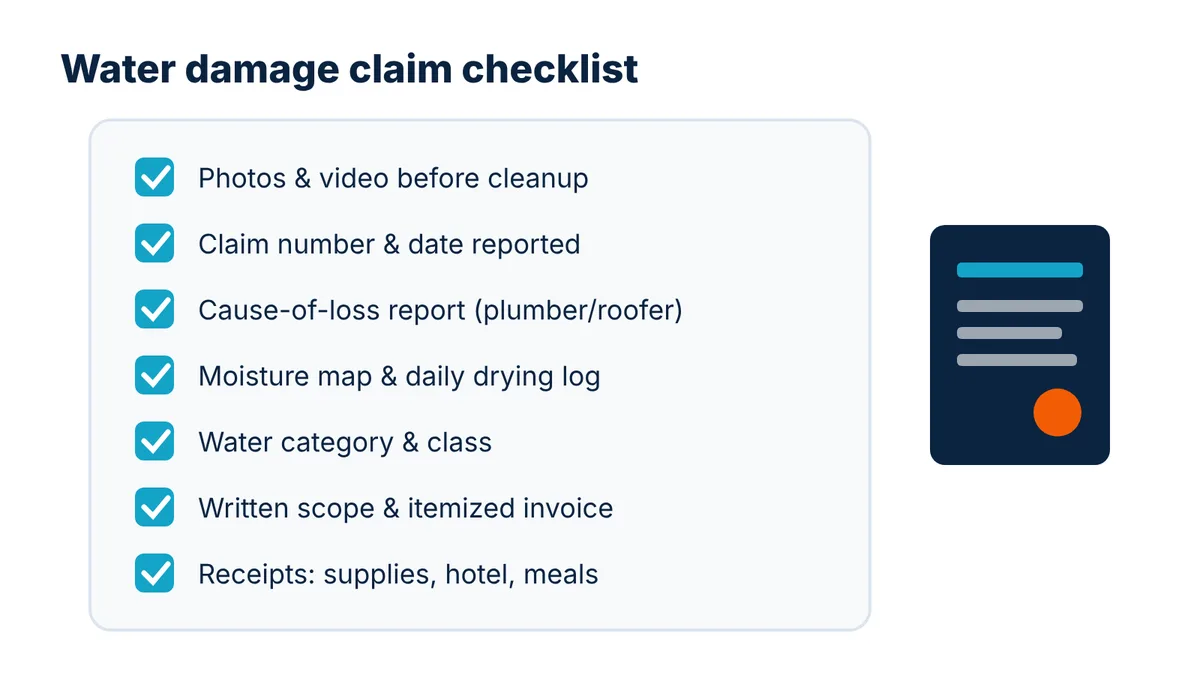
- Stop the source and take reasonable steps to prevent more damage. Most policies require this.
- Photograph and video the source, every wet room, the water line on walls and damaged items, before anything is moved.
- Report the claim to your insurance company and write down the claim number and the date.
- Start mitigation: extraction and drying. Don't wait for the adjuster to start drying.
- Keep receipts for emergency repairs, supplies, hotel stays and meals if you have to leave home.
- Keep removed items or samples (like a cut piece of carpet or the failed supply line) until your adjuster says otherwise.
Florida's assignment of benefits (AOB) ban
Florida's Senate Bill 2-A, signed in December 2022, prohibits assigning post-loss insurance benefits under residential and commercial property policies issued on or after January 1, 2023. What that means for you:
- A contractor can't take over your claim and deal with your insurer in your place through an AOB on a newer policy.
- You (the policyholder) stay in charge of the claim and are responsible for paying the contractor under your agreement with them.
- Policies issued before 2023 may still have older AOB rules, but read anything carefully before signing.
Before you sign a work authorization, check that it's a contract for services and not a transfer of your insurance rights, and ask for a written estimate or scope.
Claim reporting deadlines
The same 2022 reforms shortened the time to report property claims: generally one year from the date of loss for a new or reopened claim, and 18 months for a supplemental claim. Hurricane and windstorm claims can have their own rules. Report as soon as possible; waiting makes it harder to prove the cause and the extent of damage.
What restoration records help your claim
| Record | Why it helps |
|---|---|
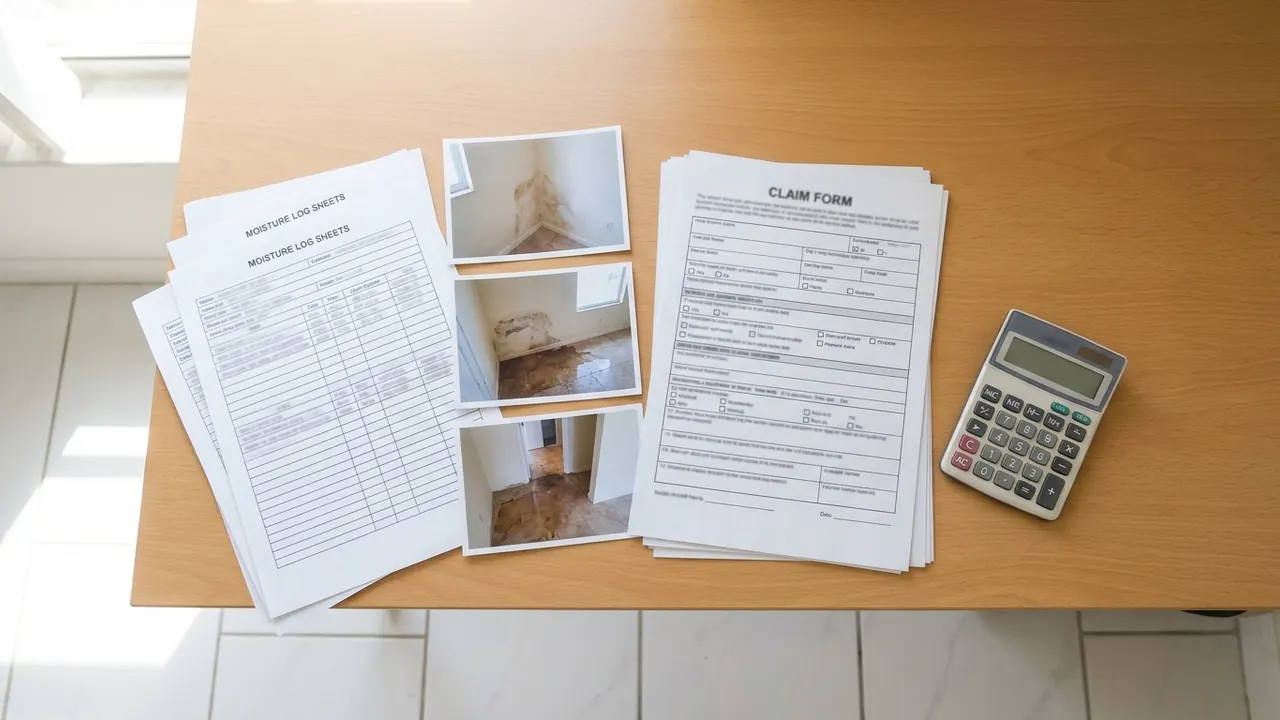
| Photos and video before, during and after | Shows the extent of damage and why materials were removed |
| Cause-of-loss notes (plumber, HVAC or roofer report) | Shows the damage was sudden and accidental, if that's the case |
| Moisture map and daily drying log | Shows what was wet and when it was confirmed dry |
| Water category and class | Explains why contaminated materials were discarded |
| Written scope and itemized invoice | Lets the adjuster match work to damage |
| Contents list with photos | Supports claims for damaged furniture, electronics and belongings |
What's usually covered and what isn't
- Often covered: sudden and accidental water discharge, such as a burst supply line or an appliance hose failure.
- Often excluded or limited: rising floodwater (needs flood insurance), long-term leaks and seepage, wear and tear, mold beyond a policy limit, and sewer backup without an endorsement.
- Storm damage: wind-driven rain through damaged roofs or windows is often handled under the homeowners policy, with a hurricane deductible for named storms.
Every policy is different. Read your declarations page and endorsements, and ask your agent.
Adjusters and getting help
Your insurer will usually assign an adjuster. Some homeowners hire a licensed public adjuster to represent them, or consult a Florida attorney for disputes. In Florida, only licensed adjusters can adjust claims for others, so a restoration company's role is to document the damage and the work, not to negotiate your claim. The Florida Department of Financial Services also offers free help to consumers with insurance questions.
For specific situations, see flood damage, storm and hurricane damage and condo water damage.
Water damage insurance questions
Can I still sign an assignment of benefits in Florida?
Not for residential or commercial property policies issued on or after January 1, 2023. Florida's SB 2-A prohibits assigning post-loss benefits under those policies.
How long do I have to report a water damage claim in Florida?
Generally one year from the date of loss for a new or reopened claim and 18 months for a supplemental claim under the 2022 reforms. Report as soon as possible.
Should I wait for the adjuster before drying my home?
No. Policies generally require you to prevent further damage. Photograph everything first, keep samples if asked, and start extraction and drying.
Will my insurance pay for drying equipment and electricity?
Mitigation costs for a covered loss are commonly included. Some insurers also reimburse the extra electricity used by drying equipment, so keep your utility bills.
Can the restoration company negotiate with my insurer?
No. In Florida, adjusting claims for others requires an adjuster license. A restoration team documents the damage and work; you, your agent, or a licensed public adjuster or attorney handle the claim.
Service area: Tamiami, FL
Serving Tamiami in west Miami-Dade, ZIP codes 33175 33182 33184. Mailing address: 14245 SW 128th St #308, Miami, FL 33186.
Open Tamiami, FL in Google Maps →
Helpful guides
- Water Damage in Your Home: What to Do in the First 24 Hours
- Filing a Water Damage Insurance Claim in Florida: A Homeowner's Guide
- Hurricane Season Water Damage Prep for Tamiami Homes
Related water damage services
Emergency Water Extraction · Flood Damage Restoration · Storm & Hurricane Water Damage · Condo & Apartment Water Damage · Water damage restoration in Tamiami